
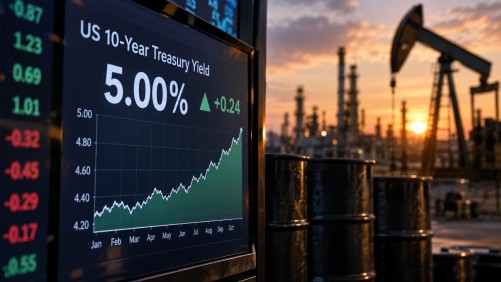
The yield on the 10-year US Treasury bond has surged to 5%, a level not seen since 2023, as global bond markets face a steep sell-off driven by climbing oil prices and mounting inflation fears. This rise marks a significant shift from earlier this year when yields hovered around 4%. The change has been steady since the conflict between the US-Israel coalition and Iran erupted in late February, which last pushed yields above 5% in October 2023.
This increase in bond yields coincides with Brent crude oil prices surpassing $108 per barrel. The energy market has been rattled by attacks on Saudi Arabian infrastructure and escalating tensions in the Middle East. Drone strikes have forced the closure of a crucial east-west pipeline in Saudi Arabia, sparking worries about potential disruptions in global oil supplies. The situation has been further strained by activities from Iran-backed Houthi forces and rising tensions near the Bab al-Mandab Strait.
Further complicating matters, Gulf states have delayed talks with Tehran regarding a temporary shipping route through the Strait of Hormuz, a vital passageway for a large portion of the world’s oil and gas supplies. The spike in energy prices is exacerbating inflationary pressures and casting uncertainty over future global interest rate trends. Investors are keenly observing the upcoming interest-rate decision from the US Federal Reserve, with the Bank of England also poised to announce its own decision shortly.
The ramifications of rising US Treasury yields are significant for worldwide financial markets, as the 10-year Treasury serves as a crucial benchmark for borrowing costs. Higher yields can lead to increased financing costs across governments, businesses, and households globally. Across Europe, bond yields are also on the rise, with the UK’s long-term government borrowing costs reaching unprecedented levels in recent decades. The combination of increasing energy prices and renewed geopolitical tensions is fueling concerns that central banks might need to maintain stringent monetary policies for an extended period.
Throughout the year, oil prices have seen significant volatility. Brent crude, which was priced around $72 per barrel before the recent conflict, peaked at approximately $126 in April. It then dipped during the summer amid hopes for a lasting ceasefire. However, prices have once again climbed past $100 as hostilities intensified and diplomatic negotiations faltered. This resurgence in oil prices has reignited market fears over inflation, interest rates, and the broader consequences of sustained disruptions to global energy and trade routes.